Should Austin buyers take an adjustable-rate mortgage with fixed rates above 7%?
An adjustable-rate mortgage can make sense for Austin buyers who expect to sell or refinance within about five to seven years, because the starting rate is lower. In early November 2026 the average 5/1 ARM was about 6.28% versus about 7.21% for a 30-year fixed (MBA). On a $378,900 loan, that start rate is roughly $209 a month less than a fixed loan at Freddie Mac's 7.11% average. The trade-off is that the rate can rise after the fixed period, so it fits best when you have a clear plan and room in your budget if it does.
By Carmen Reese | The CLR Sales Group | November 13, 2026
With 30-year fixed rates sitting above 7%, more of my buyers are asking about adjustable-rate mortgages. They've heard the word "ARM" and they're not sure if it's a smart move or a 2008 mistake waiting to happen.
The truth is somewhere in the middle. An ARM is a tool. For some families it's a great fit, and for others it's a real risk. Here's how I'd think about it.
Where rates are right now
- 30-year fixed: 7.11% on average, Freddie Mac's November 12, 2026 survey. That was the fourth straight weekly decline and the lowest in seven weeks, but it's still about a point higher than a year ago (6.24%).
- 15-year fixed: 6.45% (same survey).
- 5/1 ARM: about 6.28%, versus 7.21% for a 30-year conforming loan, in the Mortgage Bankers Association survey for the week ending November 6. ARMs made up 10.9% of applications that week.
- The Federal Reserve held its target range at 3.75% to 4.00% on October 28, and two members voted for a hike. So nobody should be planning on rates falling quickly.
NPR's Planet Money reported this month that ARMs are only about 5% of U.S. mortgages today, compared with about a third during the run-up to the housing bubble. They're coming back, but they're still a small slice.
What the lower rate actually saves
Let's use the median home price in Austin this fall, $421,000 (Unlock MLS, September), with 10% down. That's a loan of about $378,900. Principal and interest only:
- At 7.11% fixed: about $2,549 a month
- At 6.28% for the first five years: about $2,340 a month
- Difference: about $209 a month, or roughly $12,500 over five years
That's real money. But the reason the rate is lower is that you're taking on the risk of what happens after year five.
What happens when the ARM adjusts
On a 5/1 ARM, the rate is fixed for five years and then adjusts once a year, based on an index plus a margin set in your loan. Rate caps limit how much it can move. A common setup limits the first adjustment to 2 points, each later adjustment to 2 points, and the lifetime increase to 5 points, but every loan is different, so read your own loan estimate.
Here's what the same loan could look like after five years, when the balance would be about $353,800:
- If the rate reset to 8.28%: about $2,796 a month
- If it later climbed all the way to the lifetime cap of 11.28% (with the caps above, that would take several yearly adjustments): about $3,539 a month
That worst case is about $990 a month more than the 30-year fixed payment. I'm not here to pretend that couldn't happen. It's exactly why I want every buyer to look at that number before choosing an ARM, not after.
There's a more hopeful side too. Planet Money cited a Redfin analysis going back to 1971 that found ARM borrowers had at least one chance to refinance to a lower rate about 70% of the time. That's a pattern, not a promise.
If you want to see what payment works for your family before you start shopping, make sure to attend our next live Homebuyer Webinar. Register here.
Who an ARM can make sense for
- Move-up families with a five to seven year plan. If you know this is a "for now" home, you may sell before the rate ever adjusts.
- Buyers who expect their income to grow and could handle a higher payment if it came.
- Buyers with room in their budget even at the capped payment.
Who should probably stick with a fixed rate
- Forever-home buyers who plan to stay 10 years or more.
- Buyers stretching to qualify. If the starting payment is already the most you can handle, an ARM adds risk you can't absorb.
- Anyone who would lose sleep over it. Peace of mind is worth something.
Other ways to lower your rate in Austin right now
Before you choose an ARM, compare it with the options this market gives buyers:
- Seller-paid rate buydowns. With so many Austin listings cutting their price this fall, sellers are often willing to put money toward your rate instead.
- Builder incentives on new construction, which often include a buydown.
- Assistance programs for buyers who qualify, which can lower what you need to bring to closing.
Every situation is different, and the only way to know which one fits is to run the numbers side by side with your lender.
Confirm current rates, caps, and terms with your lender.
Frequently Asked Questions
What is a 5/1 ARM?
A loan with a fixed rate for the first five years that then adjusts once a year based on an index plus a margin. Rate caps in the loan limit how much each adjustment can raise it.
Is an ARM a good idea if I plan to move in five years?
It can be. If you sell before the fixed period ends, you keep the lower payment the whole time. Make sure you could afford the adjusted payment in case your plans change.
Can I refinance out of an ARM later?
Yes, if rates drop and you qualify. Refinancing costs money, and rates may not cooperate, so don't count on it as your only plan.
Is a seller-paid buydown better than an ARM?
It depends on how long you'll keep the loan and what the seller will offer. A permanent buydown lowers your fixed rate for the life of the loan, while an ARM's savings are only guaranteed during the fixed period. Compare both with your lender.
Are ARMs as risky as they were in 2008?
Today's ARMs generally require full income documentation and have caps, and they're a much smaller share of the market. The risk that remains is a higher payment after the fixed period, which is why the capped payment matters.
The bottom line
An ARM isn't good or bad on its own. It's a trade: a lower payment now in exchange for uncertainty later. For an Austin family with a clear five to seven year plan and room in the budget, it can be a smart move. For a forever home or a tight budget, a fixed rate is usually the calmer choice.
If you want help comparing a fixed rate, an ARM, and a seller-paid buydown on a real home, book a free 15-minute consult with Carmen. And if you're still figuring out your budget, start with can you afford a home in Austin in 2027.
Sources: Freddie Mac Primary Mortgage Market Survey (Nov 12, 2026); Mortgage Bankers Association weekly survey, week ending Nov 6, 2026 (reported Nov 11); NPR Planet Money via HPPR (Nov 5, 2026); Federal Reserve FOMC statement (Oct 28, 2026); Unlock MLS September 2026 Central Texas Housing Report. Payments are principal and interest only, approximate, and exclude taxes, insurance, HOA, and mortgage insurance. Rates as of mid-November 2026.
About Carmen Reese
Carmen Reese is an Austin native and the founder of The CLR Sales Group at Real Broker, LLC. She has been selling homes in the Austin area for almost a decade. Before real estate she worked as a data analyst, and she is a Certified Negotiation Expert, so every pricing and offer decision starts with the numbers. Carmen and her team are RealTrends Verified in the top 1.5% of real estate professionals nationally. She hosts the weekly Homebuyer Webinar and The Austin Homebuyer Academy on YouTube.
FROM OUR BLOG
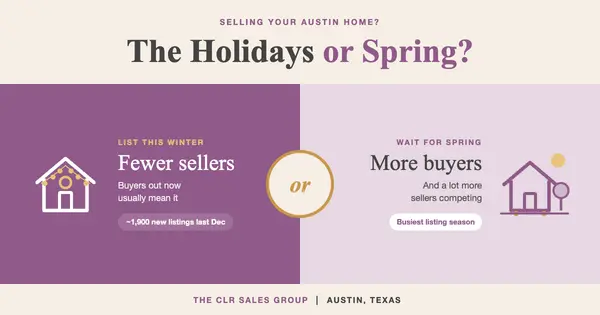
Sell Your Austin Home Over the Holidays or Wait for Spring?
Should you sell your Austin home over the holidays or wait for spring? Listing over the holidays in Austin means far less competition: Unlock MLS counted about 1,900 new listings across the Austin area last December, compared with about 3,500 this September, and closed sales held up that December. S
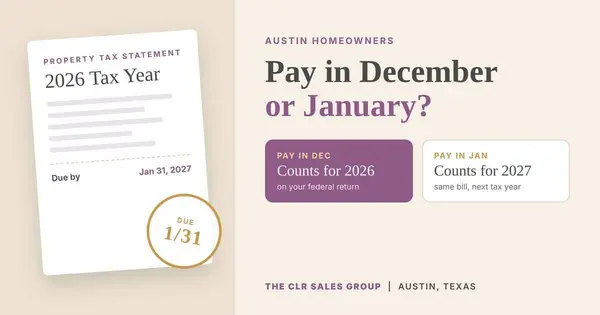
Pay Your Austin Property Tax Bill in December or January?
Should you pay your Austin property tax bill in December or January? Austin-area property tax bills for 2026 are due by January 31, 2027, and penalties start February 1. Paying in December or January costs the same, but the tax year it counts in is different: a December payment generally counts towa
Austin Rental Owners: The 20% Tax Cap Ends Dec 31
What happens when Texas's 20% appraisal cap on rental homes ends? Texas's 20% "circuit breaker" cap on non-homestead property values expires on December 31, 2026. Starting with the 2027 tax year, an Austin-area rental or second home with a capped value below market value can be appraised at its full